The asking price is not the full cost of buying a home. If you buy, let or sell property in England, you may face a different tax at each stage. Even buying a second home, or your residence status, can change the amount dramatically. In this guide we look at property tax in England through real-life situations, so you know which costs to budget for and when.
When is property tax paid in England?
Property tax is not a single payment. A buyer may pay Stamp Duty Land Tax on purchase; the person living in the home usually pays local Council Tax; and a landlord must include rental income in their Income Tax calculations. Selling, holding property through a company and passing on assets after death all have their own rules.
| Situation | Possible tax | Deciding factor |
|---|---|---|
| Buying property | SDLT | Price, first or additional home, buyer's residence |
| Living in a home | Council Tax | Property band and local council rate |
| Letting or selling | Income Tax or CGT | Taxable income or gain on sale |
This table is a first map of property tax in England. The final amount always depends on the details of the transaction and the tax year.
Council Tax: the local tax on homes
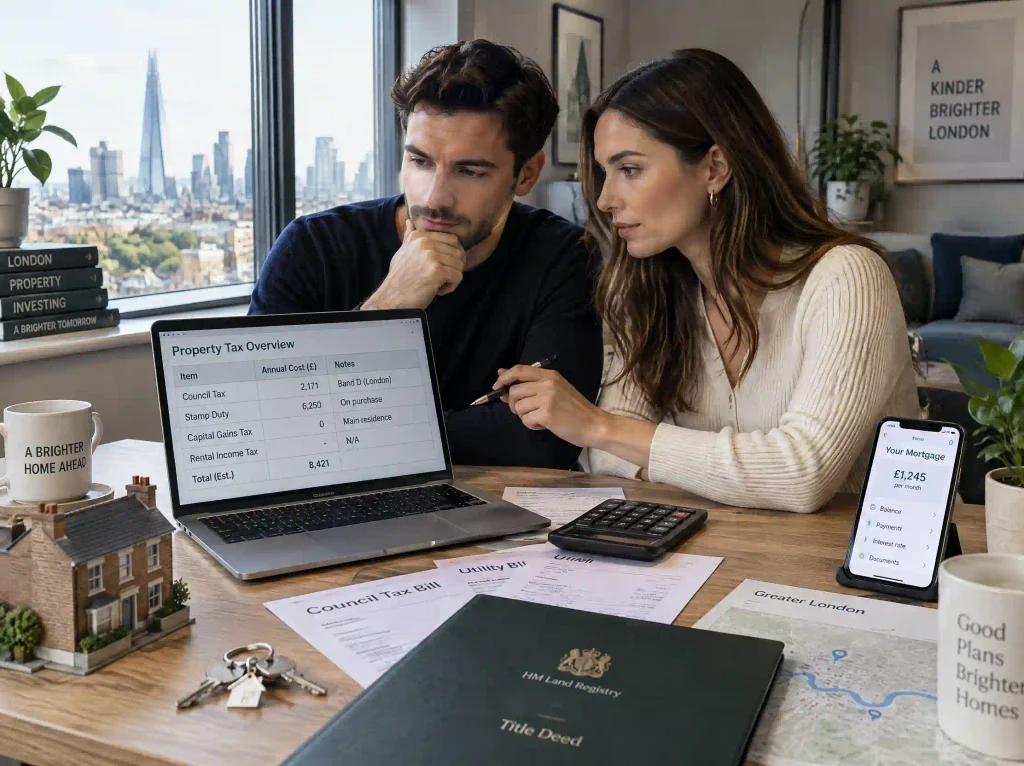
Council Tax helps fund local services and is usually paid by whoever lives in the property, so a tenant may be the one paying. Homes in England are placed in bands A to H. These bands are based on the property's estimated value on 1 April 1991, not its value today.
Each local council sets its own annual charge, so no single figure applies to every home. A single-person discount, some exemptions and the right to challenge a band also exist. Before buying or renting, check the band and annual charge on the local council's website.
SDLT: tax on buying property, and first homes versus second homes
Stamp Duty Land Tax (SDLT) applies when you buy property in England. It is calculated in slices: each part of the price is taxed at the rate for that band, rather than the whole price being taxed at one rate.
From 1 April 2025, for a standard residential purchase, the part of the price up to £125,000 is taxed at 0%. For an eligible first-time buyer, this rises to £300,000, provided the total price is no more than £500,000. Buying an additional property usually carries rates 5 percentage points higher. A buyer who is non-resident for SDLT purposes usually pays a further 2 percentage points on top.
These surcharges can apply at the same time. So if you are planning to buy a second home from outside the UK, check the result with the official SDLT calculator before you make an offer.
Income Tax on rental income: base it on real profit
Rent you receive can be subject to Income Tax, but tax is not necessarily charged on all the rent you collect. Allowable expenses, your other income, your tax residence and how the property is owned all matter. For example, qualifying repair costs may be deductible, while major improvements usually are not.
In the 2026–2027 tax year, individuals' property income is generally assessed under that year's Income Tax rules. Changes to specific property income rates have also been announced from April 2027, so you should not apply rates from an old article without checking the tax year. If you let a property, keep the tenancy agreement, expense receipts and rent payment dates in order, and read the official guidance on paying tax on rental income.
Tax on selling property: CGT and non-residents
If you sell a property for more than its allowable cost, you may pay Capital Gains Tax (CGT) on the gain. Allowable costs and the annual exempt amount can change the taxable amount. Selling a home that was your main residence throughout your ownership can usually be exempt from CGT under Private Residence Relief, although letting the property or not living there for part of the time can complicate the calculation.
CGT rates on residential property for individuals in the 2026–2027 tax year are generally 18% or 24%; the 28% figure still seen in some articles is not the current general rate for this type of gain. If the sale is taxable, UK residential property CGT usually has to be reported and paid within 60 days of completion. Non-residents also have special reporting rules for selling UK property and must report the sale in some cases even when no tax is due. Check the details in HMRC's guidance on reporting a property sale.
ATED: when a home is held through a company
The Annual Tax on Enveloped Dwellings (ATED) is an annual tax that can apply to residential property worth more than £500,000 when it is held through a company or certain similar structures. The amount depends on the property's value band and the tax year.
This does not mean every company-owned property is automatically liable. For example, relief may be available where the property is let commercially to unconnected people, though a return may still be required. Before moving a property into a company, review the ATED cost and the other tax consequences of that structure with an adviser.
Business Rates: tax on shops, offices and warehouses
For many non-residential properties, Business Rates apply instead of Council Tax. The charge is usually based on the property's rateable value and an annual multiplier. Eligible businesses may benefit from reliefs such as Small Business Rate Relief.
If the assessed value does not reflect reality, you can query it and appeal. When renting a shop, don't just compare rents; Business Rates can be a significant part of your monthly running costs.
Inheritance Tax on property: thresholds matter more than the house price
Inheritance Tax (IHT) relates to the taxable assets in an estate at death, not just the value of a single house. The standard rate is usually 40% on the part above the tax-free threshold. The basic individual threshold is generally £325,000, and in certain circumstances passing a home to children or grandchildren can unlock the additional Residence Nil Rate Band.
The spouse or civil partner exemption, the ability to use a late spouse's unused threshold and the total value of the estate all change the outcome. That is why the statement "a house under £325,000 has no inheritance tax" is not, on its own, a reliable basis for decisions.
Frequently asked questions about property tax in England
Do foreign buyers pay more tax?
If you are classed as non-resident under SDLT rules, a 2 percentage point surcharge usually applies. Nationality alone does not decide this; your status is assessed under the residence rules for this tax.
Is selling the home I live in always exempt from CGT?
No. Main residence relief depends on how the property was used and how long you owned it. Letting it out or using part of it for business can affect the relief.
Do tenants pay Council Tax?
In many residential lets, yes. However, the type of tenancy, who lives in the property and some exemptions affect who is liable.
Summary
To estimate property tax in England, first establish whether the property is residential or commercial, whether it is your first home or an additional one, whether you are tax resident, and whether you plan to live in it, let it or sell it. Then check the rates and deadlines for that tax year in official sources. This avoids surprises on completion day or after a sale.
If you need currency exchange services to buy property or pay related costs, you can ask about the services offered by Sarafi Bartar London. Sarafi Bartar is the trading name of Primores Group Ltd, registered in London under company number 13465962, and a payment services agent of Persici Financial Services Limited. For tax calculations and returns, get help from a qualified UK tax adviser.